 By Sumanta
Eastern and Western UP: A curious case of Microfinance.
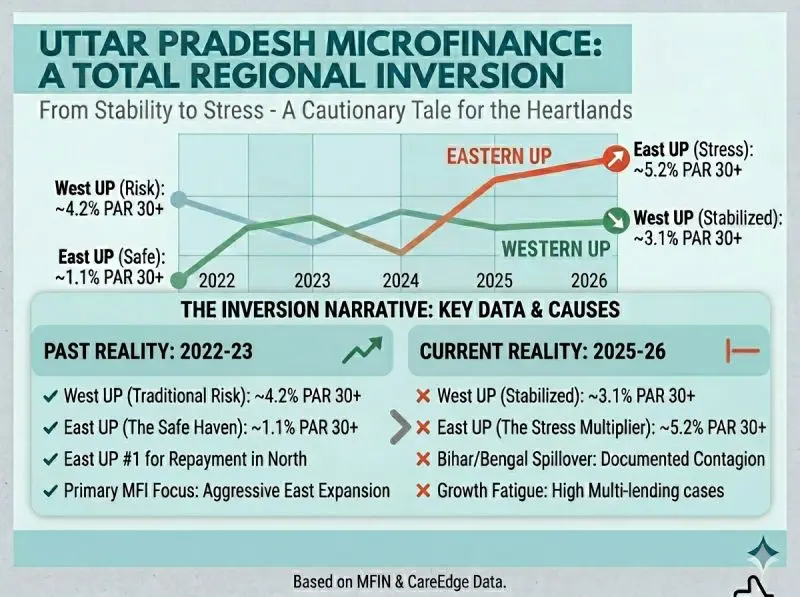
Look at the data. The legend of UP microfinance has been rewritten.
For more than a decade, the playbook was set: Western UP was the danger zone; Eastern UP was the gold standard.
That reality is dead. We are witnessing a Total Regional Inversion.
The numbers (sourced from MFIN & CareEdge, 2023-2026) tell a cautionary tale:
👉 2022:Eastern UP was a pristine 1.1% 30+ DPD.
👉 2025-26:That figure has surged to 5.2%
👉Western UP: The traditional “risk zone” did the opposite, stabilizing at 3.1%
But why?
Growth Fatigue?👉The region flooded with capital, chasing a “safe” reputation?
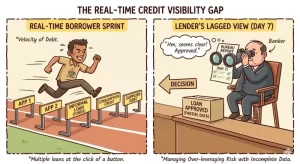
The Debt Trap ? 👉In saturated districts, 18% of borrowers now juggle 3-5 concurrent MFI loans.
Cross-Border Contagion ? 👉The high-risk behavior of neighboring Bihar leaked into Purvanchal, bringing “ghost lending” with it ?
Is cross-border risk actually a reality? Then the ripple effect of a West Bengal election will create impact in neighbouring states ?
External Shocks ?👉The combination of 2024 elections and severe heatwaves broke the sacred weekly Center Meetings ?
To me, this inversion isn’t an anomaly; it’s a systemic warning.
As a banking professional, the lesson is to not to rely always on static risk models. It has to be dynamic to ring the bell well in advance and measure the risk correctly, otherwise
We may be just documenting history.
In microfinance, sometimes you need to look at the neighbor’s house too, if you have to correctly measure your own risk !
The Bottomline: Flooding a “safe” borrower with excessive liquidity doesn’t always create inclusion, it creates a debt trap- no ?
Let’s hear your thoughts below ?👇
#Microfinance #Banking #CreditRisk #UttarPradesh #FinancialInclusion #RiskManagement #IndiaEconomy #FinTech