 By Sumanta
We are moving towards a 7-day credit bureau reporting cycle
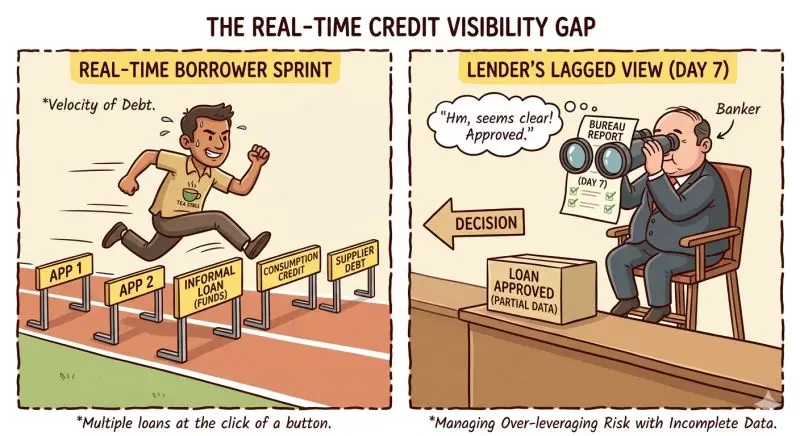
yet the “Velocity of Debt” may still outrun the “Speed of Data.”
In my 18 years of analyzing credit & risk, I’ve seen this visibility gap how fast a borrower can leverage and how slowly an institution can see it.
For a small business owner or a retail consumer, credit is no longer a “process”—it’s a button.
Between Fintechs, NBFCs, and the persistent shadow of informal lending, a borrower can technically over-leverage across multiple platforms in a single morning.
By the time that data hits the bureau 7 days later, the risk has already compounded.
We are effectively trying to manage a high-speed digital economy with a reporting system that still has a “latency” problem.
The real danger isn’t just the volume of loans; it’s the visibility gap in “Total Indebtedness.”
When reporting lags, the “Ability to Pay” is calculated on ghost data. What will FOIR policy guardrail do ?
We see the income, but we don’t see the four other micro-loans or consumption loans taken out 48 hours ago.
Let’s keep aside the reported data irregularities for the time being. That’s a more painful story.
To solve this, we, the banking fraternity needs to look beyond mere compliance.
Underwritng need to bridge the gap between “Regulatory Reporting” and “Real-Time Risk Monitoring” with balanced score card without solely depending on data based rule engine, before the next cycle of systemic stress catches us looking the wrong way.
Let’s hear your thoughts-
#BankingSimplifiedwithSumanta#Creditreporting#FOIR#Visibilitygap#CreditRisk