
Retail Credit Lab: Decoding the "Middle 40%"
Mastering the Grey Zone Beyond the Bureau Score
The "Middle 40%" — where automated scorecards reach their limit and true Lender's Intuition is required to find the Safe Yes.
Training teams to identify proprietary red flags in LAP and Personal Loans — moving beyond the surface that scoring engines never reach.
Lab I : Income Architect — cashflow forensics.
Lab II : Behavioral Profiling — intent mapping.
Lab III : Shadow-Debt Sentinel — hidden liability audit.
Cash-flow forensics on informal income. Strip out pass-through flows — lend against what the borrower actually keeps, not what passes through.
Reading live debit patterns when bureau scores go silent. Separate a recovered disciplined payer from a chronic defaulter — with evidence.
Surface undisclosed debt from bank statement patterns. Stresstest collateral beyond the valuation report. Two forensic tools. One complete Reality Audit.
 Target Group
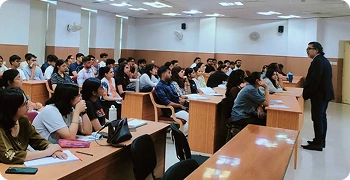
Mid-level retail credit underwriters, loan officers, and branch credit teams — typically 2–7 years of experience. Also customisable for fresher induction batches.
 Bank-Level Benefits
- Reduced NPA slippage in retail book
- Faster and more confident credit decisions
- Stronger credit culture at the ground level
- Safely unlocking the ‘Grey Zone’ segment that automated scorecards reject
Industry Leaders Say
About Sumanta


Santanu Mukherjee
Veteran Banker, Director, Industry Leader, Ex-MD of State Bank of Hyderabad
Sumanta was an excellent and energetic executive in the leadership role of Bandhan Bank with depth of knowledge in banking with special emphasis on risk management and credit controls. He is extremely innovative in handling important issues of Banking. I am sure he will earn success wherever he involves himself.

Ratan Kesh
Veteran Banker, Industry Leader, Director, Executive Director & COO-Bandhan Bank, Ex- Axis Bank
It has always been a pleasure working with Sumanta and at a personal level, I found him to be knowledgeable, committed, articulate having expertise to add value to his domain. His ability to break down complex banking concepts with clarity and precision always enhanced stakeholder’s understanding.

Deepankar Bose
Veteran Banker, Director, Industry Leader, Ex-CGM, SBI & Head CC, Bandhan Bank
It has always been a pleasure working with Sumanta since he brings profound knowledge and clarity to the domains of credit & risk management. His ability to elucidate complex banking concepts with clarity and precision, always facilitate better understanding among stakeholders.

Biswajit Das
Veteran Banker, Senior Business & Risk Leader, Ex- ICICI, CRO, CTO-Bandhan Bank
Sumanta has played a stellar role in setting up the Credit Risk function in Bandhan Bank. He has been bestowed with an important capability to break down the complex risk topics into chewable bits which becomes very easy for the risk owners to absorb and implement. He displays tenacity, perseverance and aptly mix his functional and managerial aptitude to take matters of importance to a befitting conclusion.

Prof. Bibek Ray Chaudhuri
Professor at Indian Institute of Foreign Trade. Head of Economics Division.
The sessions are well conducted covering topics relevant for Masters in Economics students and how their knowledge is utilised in Banking. Thanks for conducting such an illuminating session.

Amitava Mukherjee
Senior Industry Specialist. Equity Partner KPMG, Financial Risk Management
I strongly recommend Sumanta for his profound understanding of banking processes, regulatory frameworks and risk management, developed through his extensive experience with SBI and Bandhan Bank. His ability to simplify complex banking concepts and adapt the level of detail to suit diverse audiences demonstrates his exceptional communication and thought leadership skills.

Saurabh Jain
Senior Banker, Head of Business, Lending Kart. Ex- ICICI, ABN-Amro, Deutsche & Bandhan Bank.
I’ve known Sumanta for more than 7 years. Earlier with the largest Bank and later with a new age Private bank has given him a well-rounded experience in Credit Risk. From Micro finance and small ticket retail loans to Commercial banking and Institutional lending. He has aided in launch and scale up of various products. He never let his calmness take the better of his stand on matters which needed to have a counter view and opinion. There’s lots that one can learn by just spending few hours with him.

Achira Bhowmik
Senior Banker, Vice President-Citi. Ex- Bank of Baroda
Sumata is a very knowledgeable and thorough professional with a deep understanding of all the nuances of his subject. Having worked for over 17 years in Banking, his forte is to make the subject simple and easy to comprehend. He always had a flair for teaching, making the most complicated concepts simple breaking down it into parts that are easy to understand and relate. Have always known that his passion is to spread his knowledge. Wishing him the very best!

Shilpi Kanoria
Senior Advisor, South Asia- Climate Bond Initiative. Ex- VP, SBI Caps, Ex- IndusInd Bank.
I have been interacting with Sumanta da since his stint with SBI. He has always been conceptually very sound and more importantly, makes banking simple and easy for the clients. Communication is his strong point and he has the ability to put his points forth in a logical and easy to understand manner which enables one to move towards a win-win solution.

Ranjit Dash
Senior Banker, Credit Head, AGM-ICICI
I know Sumanta for more than a decade as a colleague as well as a peer. What stands out about Sumanta is his strong analytical mind which helps him to relate theoretical concepts effortlessly to practical problems. With almost two decades of experience as a senior banker in credit and risk function with engagements at various levels starting with a junior credit analyst to highest level of Board of Directors of a universal bank as well as Regulators has helped him to hone his knowledge and skills. These attributes combined with his natural creative persona will certainly guide him to professional success in the field of education and mentoring. I wish him all the best for his future endeavours.

Partha Ray, FIII
Industry Specialist. Senior Consultant, Cognizant.
Sumanta Chakraborty is a doyen in the field of banking and finance with in-depth knowledge and expertise in credit and risk. He demonstrated his razor-sharp analytical skills and exceptional leadership capabilities in his 18+ years of distinguished career with many feathers in his cap.

Nilanjana Biswas Mukherjee
Ex Director- Delloite. Head ECL & Model Validation- Tata Capital
Sumanta Chakraborty is a seasoned banker with exceptional judgment and a sharp command of risk management. His ability to anticipate challenges, balance prudence with growth, and make data-driven decisions consistently delivers strong outcomes. With a calm, disciplined approach and deep industry insight, he is a trusted leader in navigating complex financial environments.


